09.10.2020
How much risk is priced-in ahead of the US election?
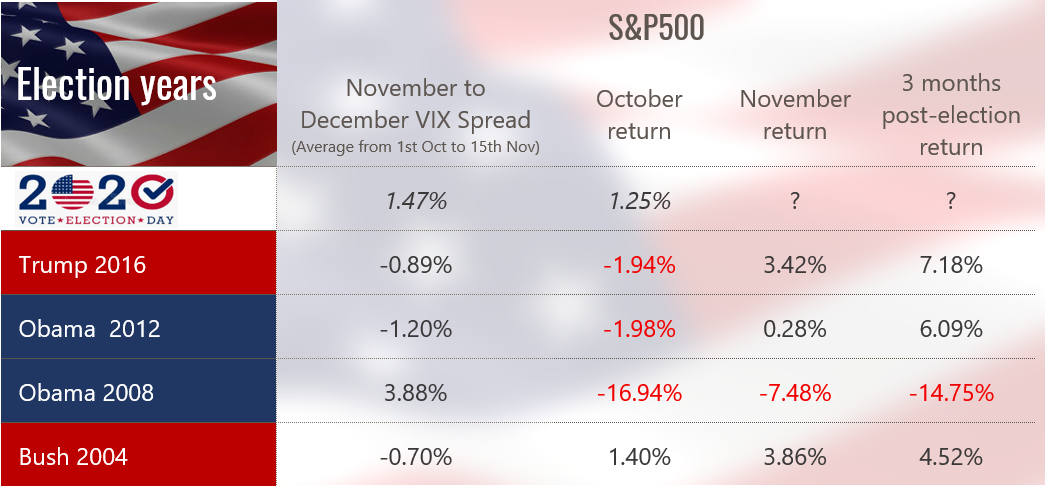
There is no doubt that a US presidential election represents a risk for financial markets and a good way to quantify how much risk is currently priced-in is to look at the forward implied volatility before and after the elections.
For that, the VIX index, a basket of the S&P 500 options volatility, sounds a good barometer.
Looking at the VIX curve, The November expiry is currently trading 1.5% above the December one, reflecting the immediate risk investors are facing post-election (November 3rd) relative to December.
While the 1.5% spread indicates a higher implied risk around and after the election, it does not quantify the absolute level of risk. To put it in perspective, we looked at the average November-December VIX Spread from October 1st to November 15th for every US Election since 2004.
Excluding the US election during the Great Financial Crisis in 2008 where spot volatility was structurally higher than 1, 2 and 3 months forward, it appears that a positive November/December VIX Spread is somewhat unusual. In fact, during the 2004, 2012 and 2016 elections, the November VIX never traded above the December one.
Looking at the return of the S&P in October, November and 3 months after the election, we can observe that it is very difficult to draw any conclusion over a US presidential election from a financial market perspective. If anything and excluding the 2008 election during the crisis, the simple and most direct conclusion would be that a US presidential election after 2000 had a positive impact on the S&P 500 Index one month and 3 months after the outcome.
So how to explain this extra-risk this time? We believe the 1.5% premium in November volatility relative to December likely reflects one single risk: if Biden wins, President Trump might not going to accept it. A sentiment that has been reinforced after the first TV debate of the US elections.
To conclude, history shows that financial markets can easily deal with a republican or democrat president but definitely not with no President after November 4th.
More articles
20.10.2026
Welcome to Dinesh Kewlram!
We are pleased to announce the arrival of Dinesh Kewlram at Cité Gestion.
Read more16.10.2026
Mental Health: A Booming Market
As one of the hardest-hit countries in Europe, mental health has been designated a major national cause in France since 2025. Faced with considerable medical needs and after decades without major innovation, new discoveries are finally emerging—notably the major resurgence of LSD.
Jérôme Berton analyzes one of the most important health issues, the main areas of innovation, and the companies positioned to benefit from them.
Link to the program14.10.2026
Will France keep financing yesterday, or start investing in tomorrow?
As debt, pension costs and interest payments rise, France risks sacrificing tomorrow's opportunities to finance yesterday's commitments.
Read more
08.10.2026
Interview - Major Trends in the Wealth Management Industry
In an exclusive interview, our CEO, Christophe Utelli, discusses the major trends in the wealth management industry as well as our response to the challenges these trends present.
Cité Gestion aims to offer independent portfolio managers a flexible approach that combines entrepreneurial freedom, operational excellence, and an international outlook. This model is supported by multi-booking, high-performance technological solutions, and access to the expanded capabilities of the EFG Group.
05.10.2026
Appointment of Bruno Cesana & welcome to Jean-Christophe Faust!
We are delighted to announce the appointment of Bruno Cesana as a banker and the arrival of Jean-Christophe Faust to the position of Chief of Staff.
Read more30.09.2026
Can the U.S. economy live with a 5% 10-year Treasury yield?
Discover why higher rates, rising mortgage costs, and expensive oil have not slowed the U.S. economy.
Read more